Ireland
Your Irish public-sector client paid 80% of your fee. That's PSWT, and you can get it back
You're a marketing consultant in Galway. A county council hires you for a tourism strategy, and you invoice €5,000 plus 23% VAT, €6,150 in all. The payment arrives on time, which is nice, but it's €5,150. Nobody has emailed to explain why.
This isn't a short payment, and you shouldn't chase it. It's Professional Services Withholding Tax (PSWT). The council has kept 20% of your fee before VAT and paid it to Revenue in your name. Here's which work it covers, how the VAT side works, and how to get the money back.
Public bodies pay fast. They just don't pay all of it
Irish government departments have a deadline. As one department's prompt payments page puts it, "All government departments have to pay suppliers within 15 days of receiving a valid invoice", under Government Decision S29296 of 19 May 2009. The departments' returns for April to June 2026 list 48,744 payments in the quarter. Defence paid 98% within 15 days. Education paid 59%, and Public Expenditure, NDP Delivery and Reform paid 55%.
So a public client is often a quick payer. But a fast payment that's 20% short is confusing if you don't know about PSWT.
Who deducts PSWT
Revenue's PSWT overview is short: "If you are an accountable person you must deduct PSWT at the rate of 20% from payments made for certain professional services." You, the person providing the service, are the "specified person". Revenue's page for accountable persons lists who they are:
- Government departments
- local authorities
- the Health Service Executive (HSE)
- authorised health insurers
- commercial and non-commercial semi-state bodies
- "any subsidiary of the above, or a body funded by any of the above."
Apart from the health insurers, that's the public sector and the bodies it owns or funds. An ordinary private company isn't on the list, so if a private client pays you short, that's a different conversation.
Does your work count as "professional services"?
Revenue's list covers medical, dental and veterinary work, architecture, engineering and surveying, accountancy and finance, "financial, economic, marketing or advertising services", legal services and geology. The detail is in Revenue's manual, Tax and Duty Manual Part 18-01-04 (last updated November 2025), which describes the category as "financial, economic, marketing, advertising or other consultancies". Its appendix answers the questions freelancers usually have:
- Design, photography and writing on their own are usually out. The manual says photography, modelling, graphic design, commercial artistry, freelance writing and printing "are not of themselves generally professional services". If you're paid directly for that work, PSWT doesn't apply "unless such service forms part of a wider consultancy."
- As part of an advertising service, they're in. When an advertising agency provides the service, PSWT comes off "the total payment (for all component services)".
- Web and IT advice is in. "Payments for independent advice on the installation, development (including the development of a web site) or running of computer systems are subject to PSWT." Selling software packages and maintaining software aren't.
- Any consultancy is in. "Note that a service, which involves the provision of advice, is a consultancy."
- Teaching is out, but designing a course is in. Teaching, training and lecturing aren't covered, but training consultancy, such as "the design/development of a course, syllabus or programme", is.
- Translation and proofreading are out. So are interpreting, stenography, cleaning, and maintenance and repair work.
Two more points from the manual. If printing or another outside service is part of a wider professional service, PSWT covers the whole payment, "even when elements of the service are separately invoiced." And a tax clearance certificate "does not negate the obligation on the accountable person to deduct PSWT."
What the 20% is worked out on
- Not the VAT. "VAT charged by the specified person should be excluded when calculating the amount of PSWT that is to be deducted." On the €6,150 invoice, PSWT is 20% of €5,000, which is €1,000.
- Yes, your expenses. PSWT applies to "the entire payment, including any element in respect of the reimbursement of expenses", such as travel, subsistence and printing, even if they're billed separately.
- Yes, late-payment interest. If the client pays you interest on a late payment for professional services, "PSWT should also be deducted from the interest."
There's a VAT point too. Revenue's page on moneys received says PSWT "is regarded, for VAT purposes, as being part of the consideration received by the supplier." Its example is a solicitor's €1,230 fee including €230 VAT. €200 of PSWT is withheld, but the solicitor "is deemed to have received €1,230 and must account for VAT of €230." In the council example, you've received €6,150 for VAT purposes, not €5,150. Our Irish VAT post covers the moneys received basis.
Getting the 20% back
When the council pays you, it files a Payment Notification with Revenue showing the gross payment and the PSWT deducted. To do that, it needs your PPSN if you're a sole trader, plus your VAT number if the payment includes VAT and the number is different. Revenue's page for providers of professional services says you can see these notifications in ROS under "PSWT Withheld From You". You can't change them, but you can download a Payment Notification Acknowledgement PDF or export a CSV. Check them against your invoices.
The money comes back in three ways:
- As a credit on your tax return. You claim the PSWT against the income tax for that year on your Form 11, and "You must include the gross amount of tax that has been withheld." Revenue's example is Jack: €40,000 of income tax for 2023 and €10,000 of PSWT withheld, so he owes €30,000.
- Not as preliminary tax. The same page says "PSWT cannot be used as payment, or part-payment, of the Preliminary Tax you owe." Revenue's pay and file manual explains how it works. PSWT is a credit that reduces your tax payable, and the preliminary tax rules then apply to that lower figure. It isn't treated as tax you've already paid. Ask your accountant to factor it in before 31 October.
- As an interim refund, during the year. If last year's profits are finalised and the tax is paid in full, you can claim back PSWT that's more than last year's liability, on Form F50A via MyEnquiries. In your first year, the manual says the credit "will not normally be given until the second tax year", so there's a separate interim refund for businesses that are just starting. There's also a hardship route, for example after a big drop in income.
If you're outside Ireland, PSWT still applies. The accountable person has to send you the acknowledgement PDF, and if you're not taxable in Ireland you claim a refund from Revenue's International Claims section, using Form IC11, a questionnaire and the acknowledgements.
What to put on the invoice
Invoice the full amount: the fee, the VAT and the total. Don't take the 20% off yourself. The public body works out PSWT and reports the gross payment, so an invoice that's already reduced makes it harder to match the Payment Notification to the invoice. Put your VAT number on the invoice if you're registered, and give your PPSN to the client's finance team on their supplier form rather than printing it. A note on the invoice is optional, but it helps the person reconciling it later, whether that's you or the council: for example, "PSWT at 20% of the fee before VAT applies (€1,000)". When the payment arrives, record €1,000 as tax withheld, not as an unpaid balance.
Where RivitPay fits
The free invoice generator, with no signup, does the layout. Put your Irish VAT number in the Tax ID field, set Tax % to 23, and the invoice shows the €5,000 subtotal, a "Tax 23%" line and the €6,150 total. Put the council's purchase order number in Reference / PO, the supply month in the line description or Notes, and your PSWT note in Notes / terms. Your IBAN and BIC go in the Payment section, so they can pay by bank transfer.
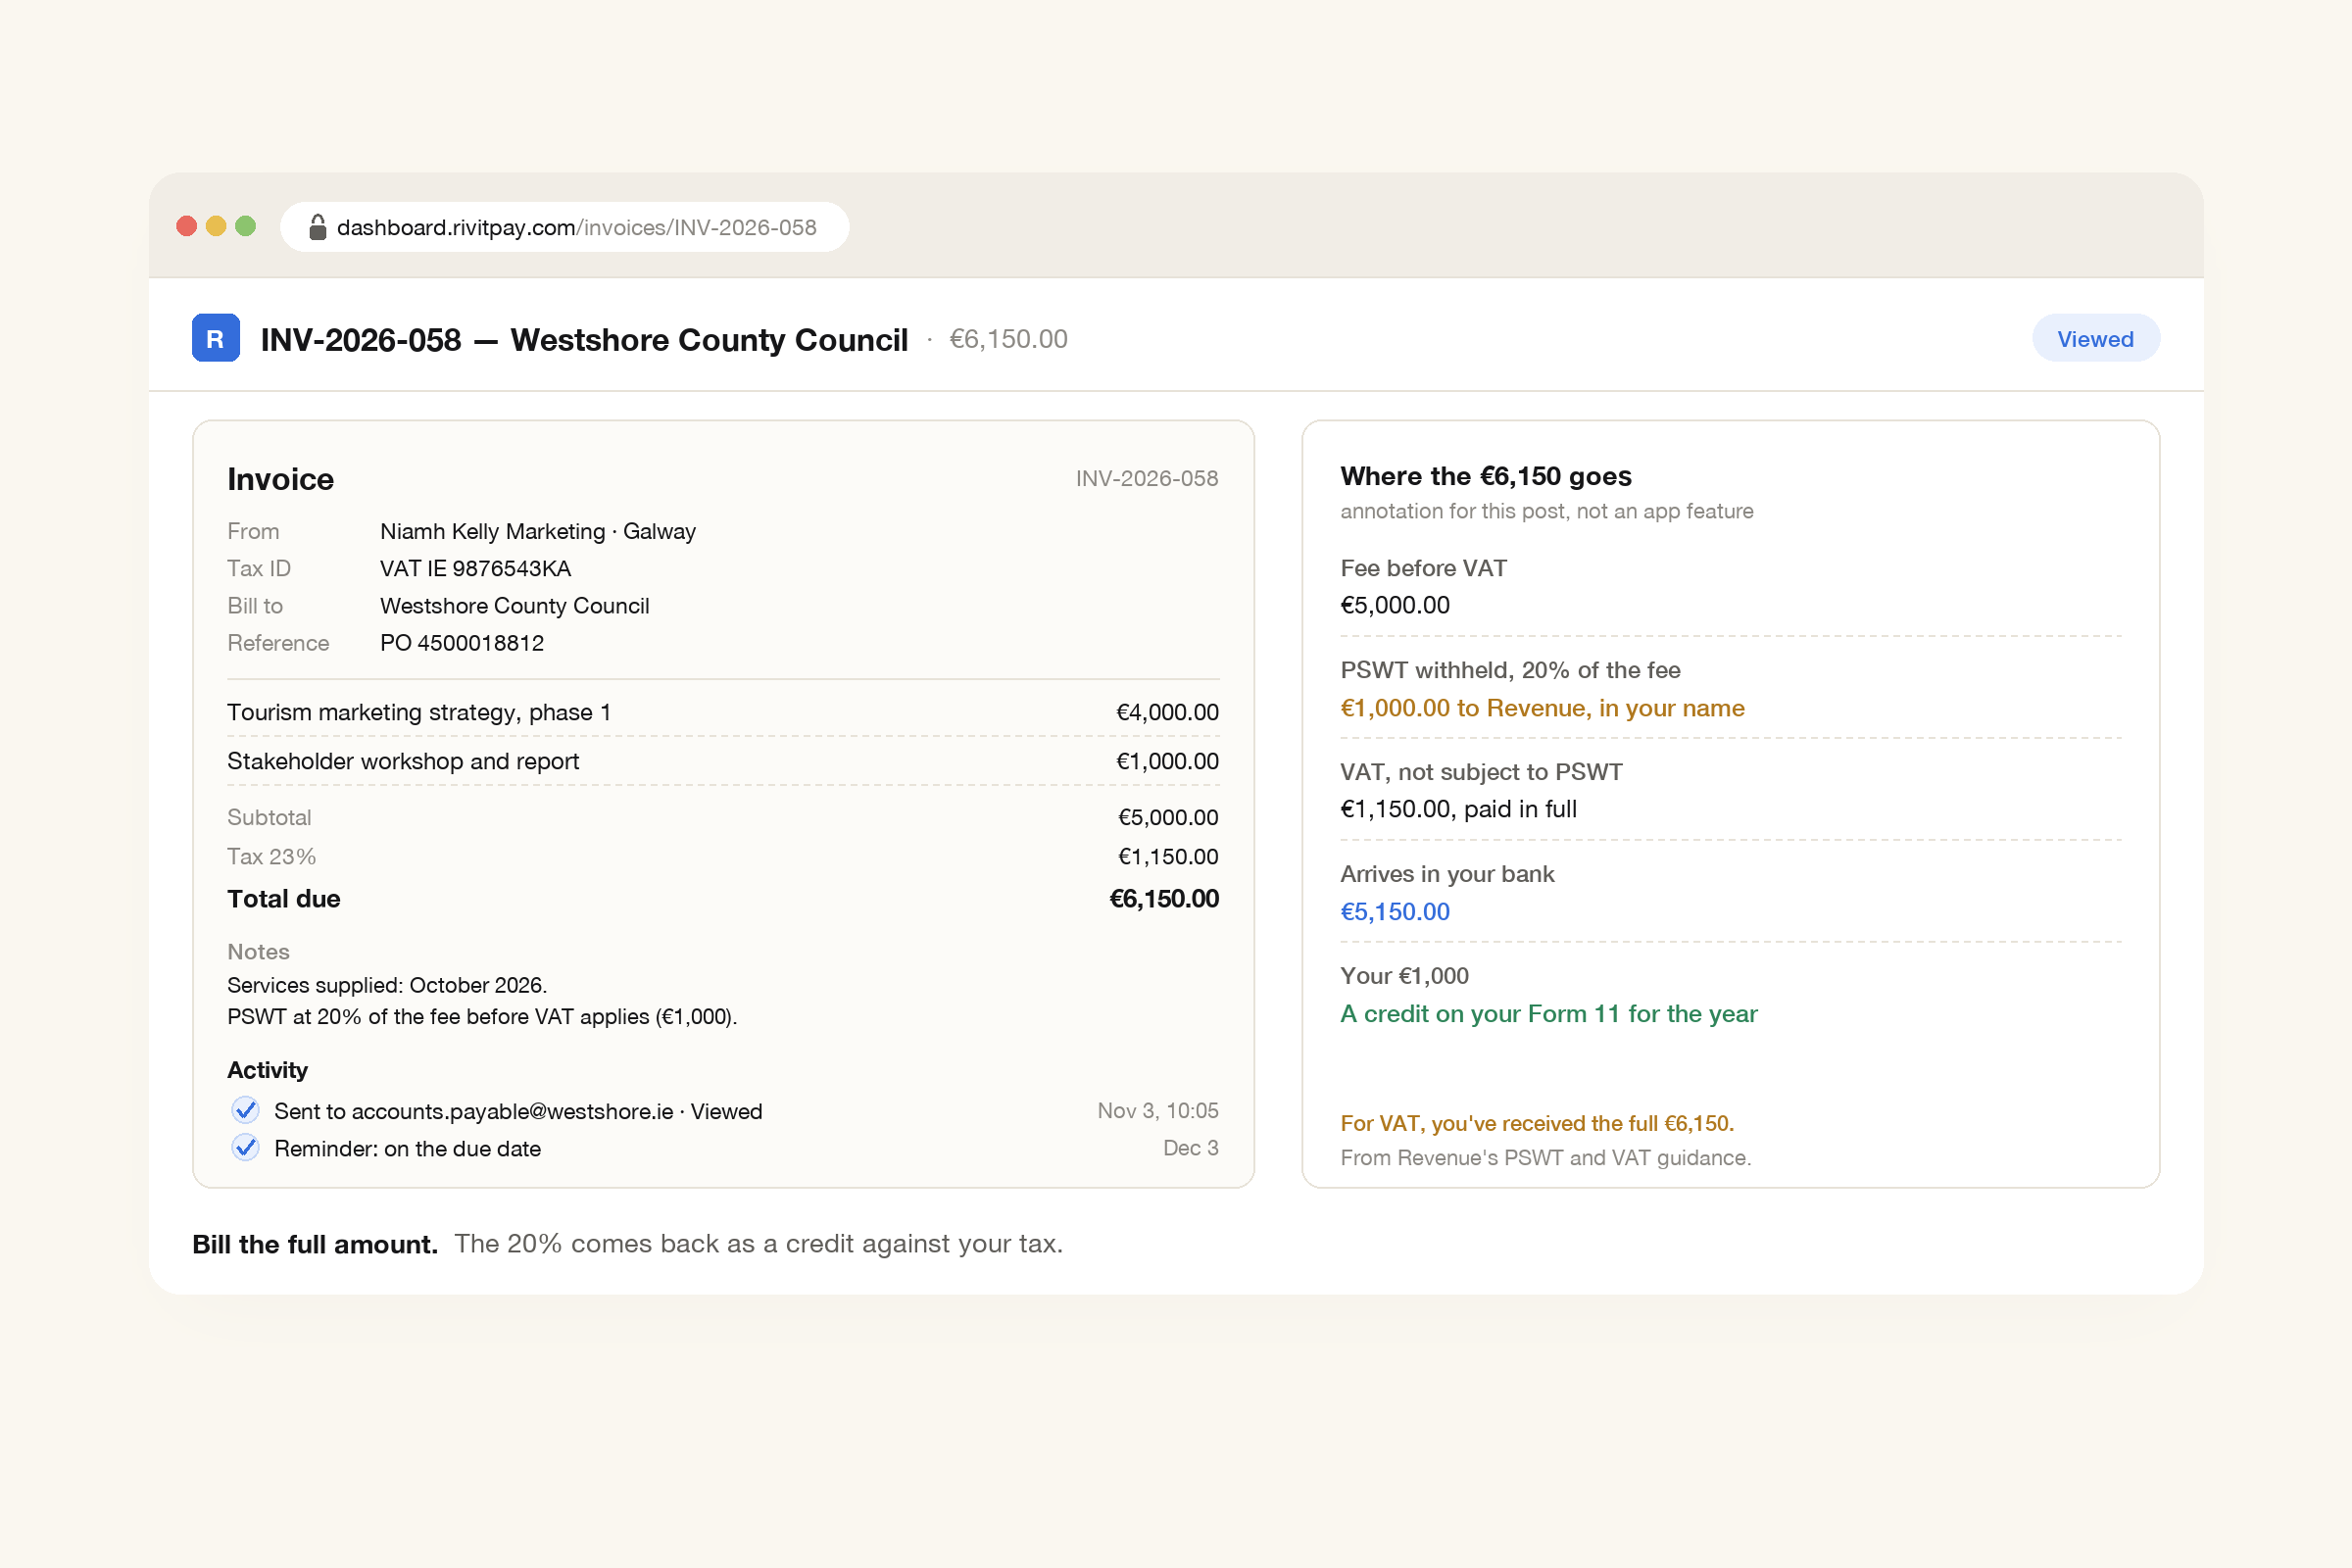
With a free account, you can email the invoice and see when the finance team opens it. Automatic reminders in your own words follow up on the schedule you set. They stop on their own when a payment comes through the Pay button. If the client pays by bank transfer outside RivitPay, check the invoice yourself so a reminder doesn't go out chasing the 20%. The receipt generator can record what actually arrived, with the invoice number on it.
The short version
If a government department, council, the HSE or a semi-state body pays you 80% of your fee before VAT, that's PSWT. It applies to consultancy, marketing, advertising, web and IT advice and similar work, but usually not to design, photography or writing on their own. Invoice the full amount, check the Payment Notification in ROS, account for VAT on the full amount, and claim the 20% as a credit on your return. If you can't wait that long, apply for an interim refund.
Your VAT number, a 23% tax line, their PO number, a note for the finance team, and your bank details printed on the invoice. Invoicing is free.
Make an invoice, free